

A Comprehensive Guide to Opening a Turkish Bank Account (Even For Non-Residents Online)

Byron Mühlberg
Guide
Melike Turan
Reviewer

An eclectic blend of East and West best known for its sweet treats, bustling bazaars, and millennia worth of human history, Turkey isn't just a much-loved destination among holidaymakers, but it's also popular among expats too.
However, moving to Turkey can be challenging, and opening a bank account in the country is high on the agenda for many new arrivals due to its necessity for daily life and business. This guide explores opening a Turkish bank account online for locals, expats, and newcomers, regardless of residence status.

In a rush? Here are our recommendations if you...
- have foreign residence: Revolut, which gives you IBAN details in Turkey (and 25 other countries) as well as a debit card to spend in 25+ currencies. You can open an account before arriving in Turkey, although you'll need to verify your address before receiving your debit card.
- have Turkish residence: İşbank, which charges comparatively good fees and offers service in English and Turkish.
Fortunately for you, opening a Turkish bank account is an easy process compared to many countries, and you can generally access a Turkish lira account without much hassle regardless of whether you're a Turkish resident or not. As we'll see in this article, there are four main paths to open a bank account online in Turkish, each depending heavily on your needs, preferences, and residence status. These paths are as follows:
- Turkish deposit banks: Ziraat Bank, VakıfBank, İşbank, and many other brick-and-mortar Turkish banks offer banking services to resident expats in Turkey. Their accounts are almost always available in English, making them a great choice for foreign residents in the country.
- International banks in Turkey: HSBC, ING, Citibank, and others sometimes offer retail banking to expats with proof of residence.
- Online banks in Turkey: Currently, only Enpara falls into this category. It also requires Turkish residence.
- Multi-currency accounts: Accounts like Wise and Revolut let you open a Turkish lira balance without Turkish residence. Wise goes a step futher still: it gives you full Turkish banking details in the form of a local IBAN account.
All About Opening a Turkish Bank Account Online
- 01. What is banking like in Turkey?
- 02. Path 1: Open a traditional bank account (Turkish residence required)
- 03. Path 2: Open a digital bank account (Turkish residence required)
- 04. Path 3: Open an account at a multinational (Turkish residence required)
- 05. Path 4: Open an account with Revolut (no Turkish residence required)
- 06. Path 5: Open an account with Wise (no Turkish residence required)
- 07. How to send money to Turkey
- 08. FAQ about how to open a Turkish bank account online
Key Facts About Banking in Turkey
| 🏦 No. of Banks in Turkey | 58 |
|---|---|
| 👨⚖️ Regulatory Body | BRSA |
| 🏆 Best Bank for Residents | |
| 💸 Best Money Transfer to Turkey | It varies. Compare now. |
| 💻 Best Account for Non-Residents | |
| 💷 Average Running Costs | ₺0 /month |
Overview of Banking in Turkey
 Svetlana Gumerova on Unsplash
Turkey has a large and developed financial sector that's dominated by both state-owned deposit banks such as Ziraat Bank and VakıfBank, as well as private deposit banks such as İşbank and Yapı Kredi. (The term 'deposit bank' is used in Turkey to refer to retail banks that allow clients to deposit funds into savings, checking, or money market accounts.)
According to the Banking Regulation and Supervision Agency (BRSA), the country's banking regulator, as of July 2023, there were a total of 58 banks in Turkey. Despite its resilience, the financial sector in Turkey has faced turmoil in the past decades. Since 2000, it has battled soaring inflation, high interest rates, bank runs, and financial instability — the ripples of which are being felt right up until the present day, where interest rates are artificially being held down despite high inflation rates.
As a bank account holder in Turkey, this means that you should be aware of fluctuations you may not be used to if you come from North America or Europe, for example, where both price inflation and the cost of borrowing have historically been comparatively stable in recent decades.
Pro tip: See the real-time exchange rate between the Turkish lira and the Euro (or any other currency, for that matter) here, where you can keep an eye on fluctuations and find the best money transfer providers by setting up a smart email alert.
Types of Turkish Bank Accounts
Turkish banks offer world-class financial services, and generally speaking, you should have no trouble accessing the banking services you're used to from your home country.
However, largely due to the macroeconomic environment in Turkey, there are a few peculiarities in certain Turkish bank accounts that set them apart from those around the world.
The types of bank accounts most relevant to expats are as follows:
- Current Account ('Mevduat Hesabı'): Synonymous with checking or current accounts in most English-speaking countries, these accounts are used to process cashless payments and are geared toward everyday use. It's likely the only account you'll need as an expat.
- Time Deposit Account ('Vadeli Hesap'): This account bears interest on Turkish lira or foreign currency deposits over a fixed-term period and historically offers higher interest rates than most other account types.
- Gold Account ('Altın Hesabı'): Something of a mix between a savings and current account, these gold-denominated accounts are offered by some (though not all) Turkish banks. Deposits are backed by physical gold and the buying and selling of precious metals is allowed. These accounts even offer most types of transactional services too (e.g. withdrawals, bank transfers, etc.)
While a current account is the account you'll probably rely on most, in practice, however, you'll generally be required to open a time deposit account at a Turkish bank, which will then automatically come with an associated current account.
Just like in most countries, opening a bank account or a banking package in Turkey (e.g. a current account combined with a savings account and other services) will always come with a debit card and, in some cases, a credit card too for an additional fee. Debit cards (known as a banka kartı in Turkish) can be used in Turkey for cashless payments and ATM withdrawals. Credit cards (kredi kartı in Turkish), on the other hand, can be used for online payments and come with a monthly credit limit as well as rewards and exclusive bonuses.
Debit cards typically can be used for free withdrawals from most ATMs across Turkey, although cash withdrawals outside of the country usually come with high fees (sometimes as high as 4% per transaction). See Monito's guide to saving money while using ATMs abroad to learn more.
What Do I Need To Open a Turkish Bank Account?
The documents you'll need to give to your bank to open an account can differ from bank to bank. In most cases, however, you'll probably need to present the following:
- A valid identification (i.e. passport or residence permit);
- Proof of Turkish residence (e.g. utility bill, rental contract, etc.);
- Tax ID Number or Foreigner’s ID Number;
- A completed application form.
Note that proof of residence is generally only required if you're opening a bank account in Turkey as a foreigner who lives in the country. If you live abroad and want to open a bank account in Turkey (e.g. for real estate investments), then the tax ID number will generally suffice.
Path 1: Deposit Banks
 Darafsh (CC BY-SA 3.0, modified)
All in all, expats in Turkey tend to have an easy time opening a bank account. So long as you have a Tax ID Number or a Foreigner's ID Number (which means you're employed or otherwise allowed to live in Turkey), most banks won't turn away your business. These days, while it's still common in Turkey to open a bank account by appointment, online applications are becoming the norm increasingly.
Perhaps the biggest perk about opening a bank account in Turkey as a foreigner is the fact that most major Turkish banks offer services in English — from internet banking right through to customer support. Another perk is that, by law, bank accounts incur ₺0 in monthly fees. Furthermore, Turkish banks usually make it easy to open a foreign currency bank account and a range of other modern and international-focused financial services, including SWIFT transfers and credit cards.
Is proof of residence required to open an account at a Turkish deposit bank? Yes and no. While most bank accounts in Turkey (especially those denominated in Turkish lira) require proof of residence, foreign currency accounts don't. What's more, the larger the amount you're planning to deposit, the more chance the bank will accept your application (even for a Turkish lira account).
Let's take a look at some of the offerings relevant to expats among Turkish banks:
İşbank
Turkey's oldest and largest private bank, İşbank has a reputation for its expat-friendly services and is widely available in English. However, due to the current monetary climate in Turkey, customers opening a current account will need to open a time deposit account alongside it (something which happens automatically when you set up your account). The following account is the standard:
- Lira time deposit account: This standard fixed-term interest-bearing account is tied to a regular current account for everyday spending. With it, you'll be able to fix your deposit terms to any period between one month and 1,096 days and set up Regular Savings Orders to move money into your current account.
In addition, you can also open a time deposit account in a foreign currency of your choice, as well as gold-backed accounts. You can calculate income on time deposit accounts in the Turkish lira, foreign currency, and gold using İşbank's deposit income calculator.
Ziraat Bank
Arguably Turkey's best-known bank, Ziraat Bank, is a state-owned banking giant that also offers English services. It provides the following account that we think is particularly interesting to foreigners:
- Turkish Lira Current Account: A standard, everyday checking account with a bank card, internet banking, and overdraft facilities.
VakıfBank
VakıfBank is Turkey's second-largest bank and offers an extensive network of branches and ATMs around the country. VakıfBank has services geared toward expats (including English customer support and multi-currency facilities), and current accounts will need to be opened alongside a term deposit or investment account.
Pros of Deposit Banks
- Wide range of financial services (e.g. overdraft, investments, credit card, etc.)
- Mostly available in English.
Cons of Deposit Banks
- All require proof of residence (unless depositing a very large sum or opening a non-TRY account).
- Costly fees on most services.
Path 2: Digital-Only Banks
 Scott Graham on Unsplash
Turkey is hot on the heels of Europe and North America in encouraging growth in its online-only banking sector. These banks, which have exploded in the EU especially in recent years, are fully-fledged banks offering all or most of the usual banking services; the main difference is that they don't operate out of branches, and banking services are online instead.
The Turkish government aims to prepare the regulatory landscape to encourage online-only banks in the coming years — a hopeful sign for the industry in the country. However, as of 2023, there is currently only one digital-only bank in the country:
Enpara.com
Enpara.com is Turkey's first online-only bank. It provides low-cost banking services via the internet and mobile platforms at significantly lower costs than the traditional deposit banks we explored above.
Like traditional banks, Enpara.com offers term accounts (in Turkish lira, US dollar, or Euros), savings accounts, and gold current accounts to users alongside a fee-free debit card and low-cost domestic and international bank transfers.
Pros of Online-Only Banks
- Low costs for most services.
- Seamless interface on web and mobile.
Cons of Online-Only Banks
- Only provides core banking services (e.g. current account, card, etc.).
- No bank branches.
Path 3: Multinationals
 Håkan Dahlström (CC BY 2.0, modified)
Turkey is home to a large number of big-name foreign multinational banks, including Deutsche Bank, Citibank, HSBC, ING, ICBC, Société Générale, JPMorgan Chase, and more than two dozen others. However, most of these banks offer only corporate and investment services, with only the following offering extensive services to retail customers too:
HSBC
A British banking giant, HSBC is one of the largest banks in the world, with more than 40 million customers across dozens of countries. In Turkey, HSBC is headquartered in Istanbul and offers the following account (which requires proof of residence to apply):
- Modern Account: An interest-bearing current account package available in Turkish liras, British pounds, US dollars, or Euros that supports cash withdrawals, direct debits, and standing order payments in a day-to-day transactional capacity.
HSBC also separately offers time deposits, gold deposits, and multi-currency accounts.
The YUVAM Turkish Lira Time Deposit Account is designed for non-resident individuals and foreign nationals who want to invest their foreign currency savings in Turkey with protection against exchange rate fluctuations.
Eligible applicants include Turkish citizens living abroad, Blue Card holders, and foreign nationals who can open bank accounts in Turkey. To open an account, you need to provide identification, proof of foreign residence, and a Turkish tax number, then convert your USD, EUR, GBP, or CHF funds into Turkish lira at the Central Bank’s buying rate through a participating Turkish bank branch.
The account offers flexible deposit terms of 3, 6, 12, or 24 months, with an additional guaranteed return from the Central Bank ranging from 1% to 4% annually, depending on the maturity period. At maturity, your principal is protected against exchange rate losses, and you receive interest plus the additional return. Be aware that early withdrawal results in forfeiting interest and potential principal loss due to exchange rate adjustments.
YUVAM is an option for foreigners to invest in Turkish lira with Central Bank-backed protection, but for daily use, Revolut or Wise are better options.
To learn more about the YUVAM account, visit HSBC's YUVAM official page.
ING Bank
Since 2007, Dutch bank ING has maintained a substantial presence in Turkey, serving retail and corporate clients. The major account offering relevant to expats is the following:
- Current Account: A standard current account that comes with a credit card and everyday transactional functionality. The account has no monthly fees, but the credit card costs a once-off ₺160.
Pros of Multinational Banking
- Widely available in English.
- Wide range of financial services (e.g. overdraft, investments, credit card, etc.)
- Large and trusted banks with global reputations.
Cons of Multinational Banking
- All require proof of residence (unless depositing a very large sum or opening a non-TRY account).
- Costly fees on most services.
Path 4: Receive SWIFT Transfers in TRY With a Revolut Account
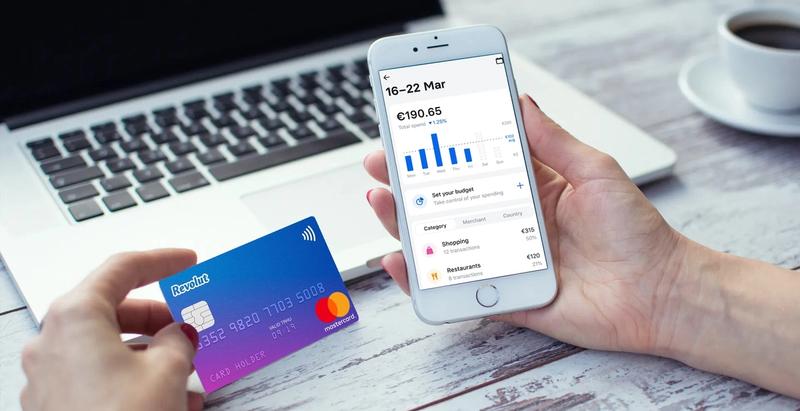
Our recommendation for non-residents who want to accept SWIFT payments from abroad to an account in Turkish lira is the Revolut multi-currency account. It comes with a virtual or physical debit card, which you can use to spend like a local in Turkey.

You can open a Revolut TRY account if you are a resident of the EU, EEA, Switzerland, USA, UK, Australia, Canada, Singapore, or Japan.
- US customers get access to a US account number, UK sort code, and IBANs for SWIFT payments to 25 currencies.
- UK or EU citizens receive a UK sort code, EU IBAN, and IBANs for SWIFT payments to 25 currencies.
Once you're signed up, you'll be able to access a Turkish account and a bunch of other features useful for expats:
- Debit card with no foreign transaction fees.
- Revolut international money transfer service from the app.
- Discounted airport lounge access.
- Access to travel and purchase insurance for paid members.
Using Your Revolut TRY Account
There are two options we recommend for using your Revolut account to receive, hold, and spend Turkish lira:
- Option 1 is to send your home currency to Revolut via local transfer, then convert those holdings to TRY using Revolut's transparent exchange rates (usually 0.4% - 2%. The mid-market rate is sometimes used for common currencies). You can see the exact rate at the checkout page. Once your account is funded, you can pay with your Revolut debit card and use your TRY currency account like a local in Turkey.
- Option 2 is to send money to Revolut's Turkish lira account via SWIFT, which is the most direct option. However, you may be subject to FX markups from the sending bank. Ask the sender to choose the ‘OUR’ option to avoid intermediary correspondent bank fees.
Pros of Revolut
- Multi-currency account and card with no monthly fee.
- No proof of residence is required in Turkey.
- Cheap money transfers to and from the Turkish lira.
Cons of Revolut
- Travel insurance and some travel perks for paid members only.
- Incoming local Turkish payments not supported.
| Revolut | Turkey |
Path 5: Receive Local Transfers in Turkey With a Wise Account
 Wise
In our opinion, the best option for an account that can accept local Turkish lira transfers as a non-resident is Wise's Multi-Currency Account. The one limitation, however, is that you won't be able to accept international SWIFT payments using this IBAN account.
Alongside its accompanying virtual or physical Visa debit card, Wise allows you to pay and be paid like a local within Turkey.
Fortunately, after opening your account online, you'll only be required to verify your identity through their interface. You won't need to show proof of residence in Turkey to sign up and obtain the Visa debit card (although you will need proof of residence in the EU/EEA, US, Singapore, Japan, Australia, Canada, or New Zealand to sign up). Here's what Wise has to say about opening an account without proof of residence in the UK, although the same applies in other countries:
"You can then choose to either supply proof of address from a standard list of documents, or to send in a selfie, in which you're holding your proof of ID. This can be a great alternative if you're still waiting to move to the UK or haven't yet got bills and other paperwork registered in your name."
Regardless of whether you have a virtual or physical card, once you're signed up for Wise, you'll be able to take advantage of the following unique features:
- Local bank details in Turkey, the US, the Eurozone, the UK, Australia, New Zealand, Singapore, Romania, Canada, and Hungary.
- Hold, exchange, and top-up up to 56 currencies.
- A multi-currency Visa debit card that's handy for paying in foreign currencies without hidden fees.
- Access to Wise's powerful international money transfer service right from your account balance.
To get a sense of how helpful Wise can be for expats, let's say that you've just moved from Germany to Turkey and would like to spend in liras before you've got your proof of residence sorted out. With the Wise Multi-Currency Account, you'll be able to:
- Send Euros from your bank account to your Wise Turkish lira account;
- Convert to liras at a low fee of around 1.16% or €3.88 to buy ₺10,000 with euros,
- Pay with your Wise debit card, make or receive SEPA (and SWIFT) payments, and set up direct debits.
You'll also have dedicated Turkish bank details to share with friends, colleagues, or even your employer. This comes in the form of a Turkish IBAN, which you can use to send and receive money within Turkey in the same way as an ordinary Turkish bank.
Pros of Wise
- Low-cost, handy multi-currency account and card.
- No proof of residence is required in Turkey.
- Cheap money transfers to and from the Turkish lira.
Cons of Wise
- Doesn't offer overdraft, and you won’t earn interest on any in-credit balances.
- Incoming SWIFT payments not supported.
| Wise Multi-Currency Account | Turkey |
Which Bank Is Best in Turkey for Foreigners?
The best bank in Turkey for foreigners and non-residents will depend on your needs and preferences and other factors such as whether or not you speak Turkish or whether or — perhaps most importantly — whether not you have proof of residence in the country. To get a better picture of how the different options we've explored compare, take a look at the table below, which gives a snapshot comparison of the relevant account offerings at Ziraat Bank, ING, Wise, Revolut, and Enpara.com:
 |  |  |  |  | |
| Bank | |||||
| Provider | Bank | Bank | Bank | Neobank | Neobank |
| Account | |||||
| Card Type | Visa/Mastercard/Troy debit¹ | Mastercard debit¹ | Mastercard credit | Visa/Mastercard debit | Visa/Mastercard debit |
| Language(s) | English, Turkish | Turkish | English, Turkish | English and 19 others | English, Turkish and 14 others |
| Currencies | TRY | TRY, USD, EUR² | TRY | TRY and 25+ others | TRY and 50+ others |
| Monthly Fee | ₺0.00 | ₺0.00 | ₺0.00 | ₺0.00 | ₺0.00 |
| Residence Required? | ✔ | ✔ | ✔ | ✘ | ✘ |
| Ideal For | Those looking for a fully-fledged bank account with multiple services. | Turkish residents looking for a low-cost banking solution. | English-speaking Turkish residents looking for an everyday curent account. | New arrivals in Turkey looking to spend and withdraw cash before acquiring a local bank account. | New arrivals in Turkey looking to spend and withdraw cash before acquiring a local bank account. |
| Try Ziraat Bank | Try Enpara | Try ING | Try Revolut | Try Wise |
Last updated: 11/19/2023
¹ Credit card upon request.
² USD and EUR for term deposit account only.
How To Send Money to a Turkish Bank Account
 Thomas Lefebvre on Unsplash
If you're moving in from abroad, you'll need to consider how to transfer your funds into your new Turkish bank account. (This process can be especially costly if you're depositing money from a currency other than liras.) To deposit money into your new Turkish lira account from your home currency before you move, you'll need to go to your online banking and choose between one of two options:
- Sending a wire transfer through your bank directly;
- Sending a bank transfer via a money transfer specialist.
In general, we don't recommend using your bank to transfer money internationally, as the fees can be exorbitant and the waiting times can be lengthy. This is mainly because banks wire funds over the SWIFT network, which adds many timely and expensive steps to the money transfer process.
Instead, if the amount you'd like to send to Turkey is in the order of several hundred or thousand US dollars or equivalent, then we recommend you use a money transfer specialist service (Wise is generally the cheapest to Turkey from countries such as Germany, the US, and the UK.) To compare which services are cheapest for your transfer amount and home country to Turkey, run a search on Monito's real-time comparison engine here.
On the other hand, if you're moving large amounts of money from your home currency to your new bank account in Turkey (i.e. anything upwards of USD 30,000 or equivalent), then services such as Wise may not be your cheapest bet. Instead, we recommend exploring your options among the foreign exchange brokers that support transfers from your country to Turkey. These services specialise in negotiating favourable exchange rates on your behalf and are the most cost-effective option for transferring large sums of money (such as life savings or liquid investments) across borders.
To find out which service will offer you the best deal in real-time, run a search on our comparison engine below:
Compare leading money transfer providers in real-time:
Recap: The Best Online Bank Accounts in Turkey
To conclude, let's recap the main recommendations we explored in this non-resident banking guide:
FAQ About Opening a Turkish Bank Account
Non-Resident Bank Accounts in Turkey vs Other Countries
Many countries allow non-residents to open a bank account within their legal jurisdictions, but exactly what kind of requirements non-residents face can differ drastically from country to country and even bank to bank. See the list below to get a better idea of this:
| Country | Which non-residents can open an account? |
|---|---|
Parties with close ties, expats, immigrants, investors, students | |
Any interested party | |
Parties with close ties | |
Parties with close ties, investors, students | |
Parties with close ties, Investors | |
Investors only | |
Parties with close ties, investors, students | |
Parties with close ties, investors, expats, students | |
Parties with close ties, investors | |
Parties with close ties, investors | |
Parties with close ties, investors | |
Parties with close ties, investors | |
Parties with close ties, investors | |
Parties with close ties, investors | |
Any interested party | |
Parties with close ties, investors | |
Investors only | |
Investors only | |
Parties with close ties, investors, expats | |
Parties with close ties, investors, expats | |
Any interested party |
Last updated: 23/2/2022
Other Banking Guides for Non-Residents


Why You Can Trust Us
You’re probably all too familiar with the often outrageous cost of sending money abroad. After facing this frustration themselves back in 2013, Monito co-founders François, Laurent, and Pascal launched a real-time comparison engine to compare the best money transfer services worldwide.
Today, Monito’s award-winning comparisons, reviews, and guides (no longer just about money transfers but also digital accounts, travel cards, eSIMs, and travel insurance) are trusted by millions each year. Our recommendations are backed by our comparison data and dozens of expert tests, allowing you to confidently make the savviest decisions.

15+ million people across the globe trust Monito.

Monito's experts spend hours researching and testing services

Commissions we may receive never impact our independence.